Fuel Switch Snapshot: B100 premiums narrow in Rotterdam and Singapore
LBM's premiums over B100 widen by $99-102/mt in Rotterdam
Singapore's LNG (diesel SS) flips to $29/mt discount to LSMGO
B100 demand increases in Rotterdam
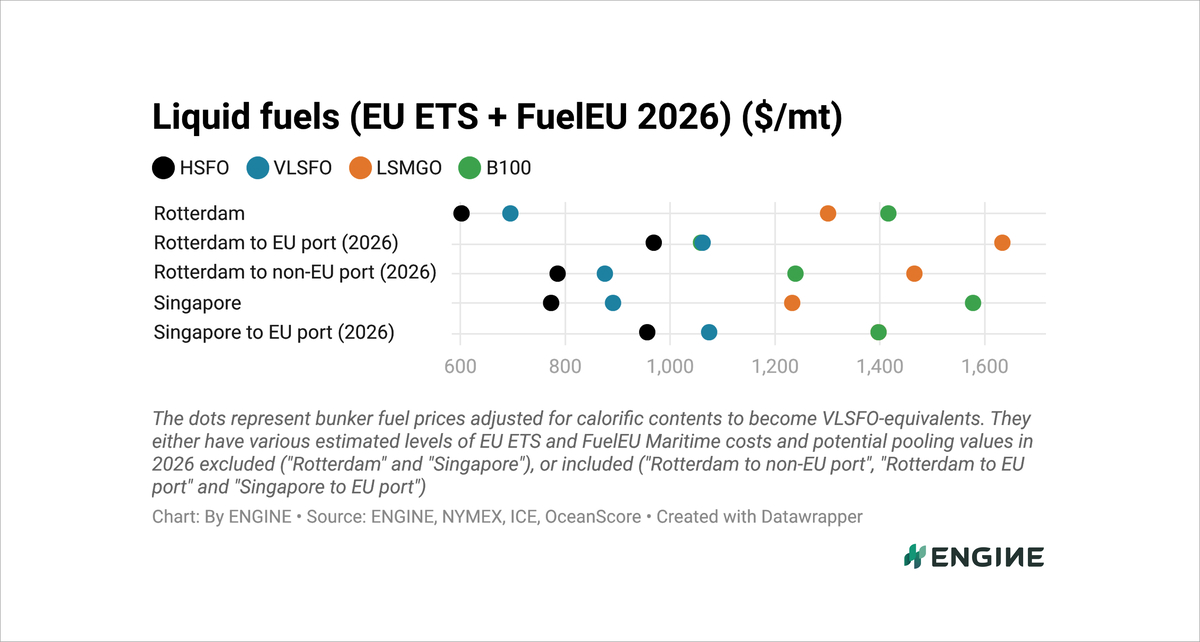 All bunker prices described in the text below have been adjusted for calorific content to make them VLSFO-equivalent. They have estimated EU-EU voyage compliance costs included for Rotterdam, and nonEU-EU compliance costs included for Singapore. These account for EU ETS costs and FuelEU Maritime penalties, and the average price of compliance surpluses we have picked up from the FuelEU pooling market over the past week.
In Rotterdam, B100 has swung from a $40/mt premium over VLSFO to a $1/mt discount. B100 has fallen by $48/mt, while VLSFO has dipped by $7/mt.
Rotterdam's B100 premium over HSFO has narrowed by $20/mt to $90/mt, as B100 has fallen further than HSFO. B100's discount to LSMGO in the port has narrowed by $1/mt to $573/mt, as both fuels have fallen by similar amounts.
In Singapore, B100's premium over VLSFO has narrowed by $15/mt to $326/mt, as VLSFO has gained $30/mt and B100 $16/mt. B100 has remained level with LSMGO in the port.
OceanScore's FuelEU pooling index has been unchanged at €108.60/mtCO2e ($122/mtCO2e) over the past week, but a weaker euro has lowered its dollar value by $2/mtCO2e. This has trimmed the pooling value of B100's compliance surplus by $5/mt to $360/mt on intra-EU voyages, and by $2/mt to $180/mt on extra-EU voyages.
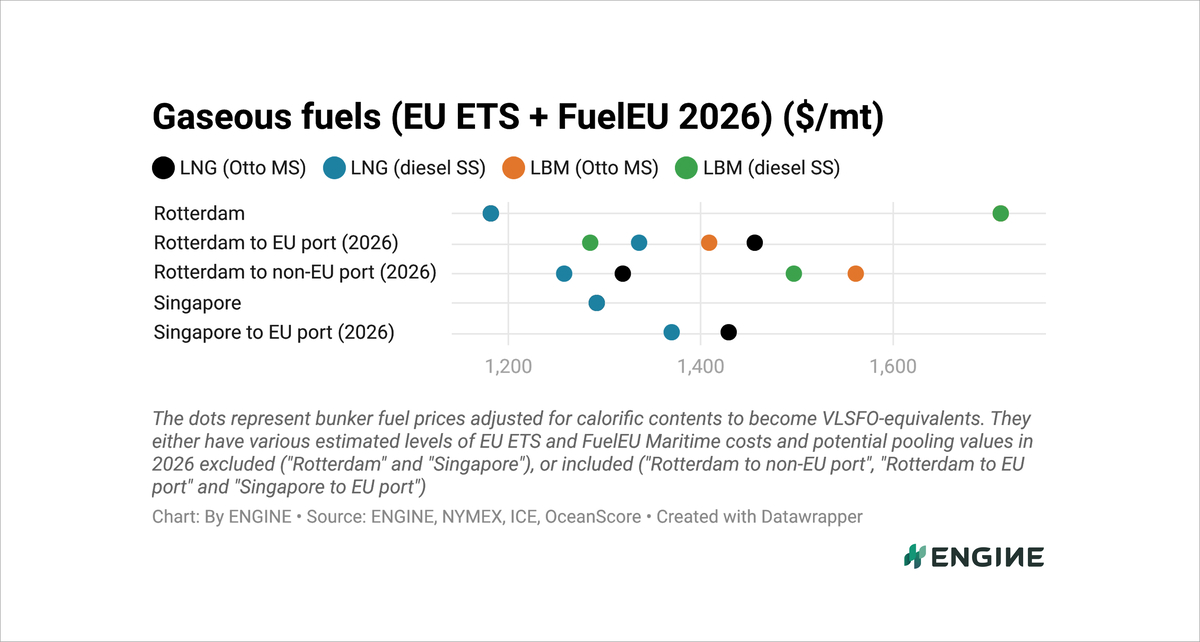
Liquefied biomethane's (LBM) premiums over HSFO in Rotterdam have widened by $79-82/mt to $315-440/mt depending on engine type, as LBM has gained $51-54/mt while HSFO has fallen by $27/mt.
LBM's premiums over VLSFO have widened by $59-62/mt to $224-349/mt, and its premiums over B100 have widened by $99-102/mt to $225-350/mt, as LBM has gained $51-54/mt while VLSFO has dipped by $7/mt and B100 has fallen by $48/mt.
LBM's discounts to LSMGO have narrowed by $100-103/mt to $223-349/mt, with LBM rising and LSMGO falling by similar amounts. The pooling value of LBM's compliance surplus has slipped by $5-6/mt to $370-433/mt depending on engine type, on the weaker euro, and the smaller credit has added to LBM's rise.
Rotterdam's LNG premiums over VLSFO have widened by $33-35/mt to $275-396/mt depending on engine type, as LNG has gained $25-28/mt while VLSFO has dipped by $7/mt. LNG's discounts to LSMGO in the port have narrowed by $74-77/mt to $176-297/mt, driven mainly by LSMGO's $49/mt fall.
In Singapore, LNG's premiums over VLSFO have narrowed by $46-47/mt to $296-357/mt, as VLSFO has gained $30/mt and LNG has fallen by $15-17/mt.
LNG burnt in diesel slow speed (diesel SS) engines has flipped from a $1/mt premium over LSMGO in Singapore to a $29/mt discount, as LNG (diesel SS) has fallen by $15/mt while LSMGO has gained $16/mt. Singapore's B100 has gained by a similar amount, so it has swung from a $1/mt discount to LNG (diesel SS) to a $30/mt premium.
LNG burnt in Otto medium speed (Otto MS) engines has held its premium over LSMGO in Singapore, though that premium has narrowed by $32/mt to $31/mt.
Liquid fuels
Rotterdam's conventional fuel prices have fallen by $7-49/mt over the past week, with LSMGO down the most.
Rotterdam's B100 has fallen by $48/mt, with a smaller pooling credit holding back part of the fall.
Dutch ZRE A tickets have fallen by €2.50/mtCO2e ($5/mtCO2e) to €172.50/mtCO2e ($194/mtCO2e) over the past week, Prima Markets said.
Prompt availability has been tight in all three ARA ports, with lead times of 5-7 days recommended, a trader said. B100 demand has been increasing in Rotterdam, with ENGINE's fuel quality data showing a sharp rise in the number of B100 bunker samples recorded in the port between January and August, compared with the same period last year.
Singapore's conventional fuel prices have risen by $16-43/mt, with HSFO up the most. Singapore's B100 has gained $16/mt, with a smaller pooling credit adding to the rise.
Singapore's bunker market has remained tight, with lead times of 10-15 days advised for VLSFO and HSFO. LSMGO has been available more promptly, with lead times of about five days.
Front-month ICE Brent futures have fallen by $3.31/bbl ($24/mt) to $101.50/bbl ($744/mt) over the past week, as the front month has rolled from November to December. The December contract itself has gained $4.17/bbl ($31/mt) over the same period.
Dec26 EUA prices have fallen by $3.28/mtCO2e to $93.91/mtCO2e.
Liquid gases
Rotterdam's LNG prices have gained $25-28/mt depending on engine type over the past week, while its LBM prices have risen by $51-54/mt.
European gas prices have drawn support from pressure to replenish low stockpiles, ANZ Bank's senior commodity strategist Daniel Hynes said. Rising supply from the Middle East has failed to dent concerns about shortages over the coming heating season, he added, and Mind Energy said concerns about winter supply are high.
LBM's discounts to LNG in Rotterdam have narrowed by $26/mt to $47-51/mt, with the same narrowing on both engine types.
Singapore's LNG prices have fallen by $15-17/mt depending on engine type.
The front-month Japan/Korea Marker (JKM) has declined on subdued buying interest in East Asia and expectations of a mild winter, the Japan Organization for Metals and Energy Security (JOGMEC) said.
China and Japan have been largely absent from the market ahead of the winter heating season, Hynes said. The lack of urgency has been exacerbated by Indian buyers slowing their LNG purchases, he added.
By Erik Hoffmann
Please get in touch with comments or additional info to news@engine.online