East of Suez Fuel Availability Outlook 15 Sep
VLSFO and HSFO availability tight in Singapore
Bad weather keeps bunkering halted in Zhoushan’s outer anchorages
Bunker availability tight across several Japanese ports
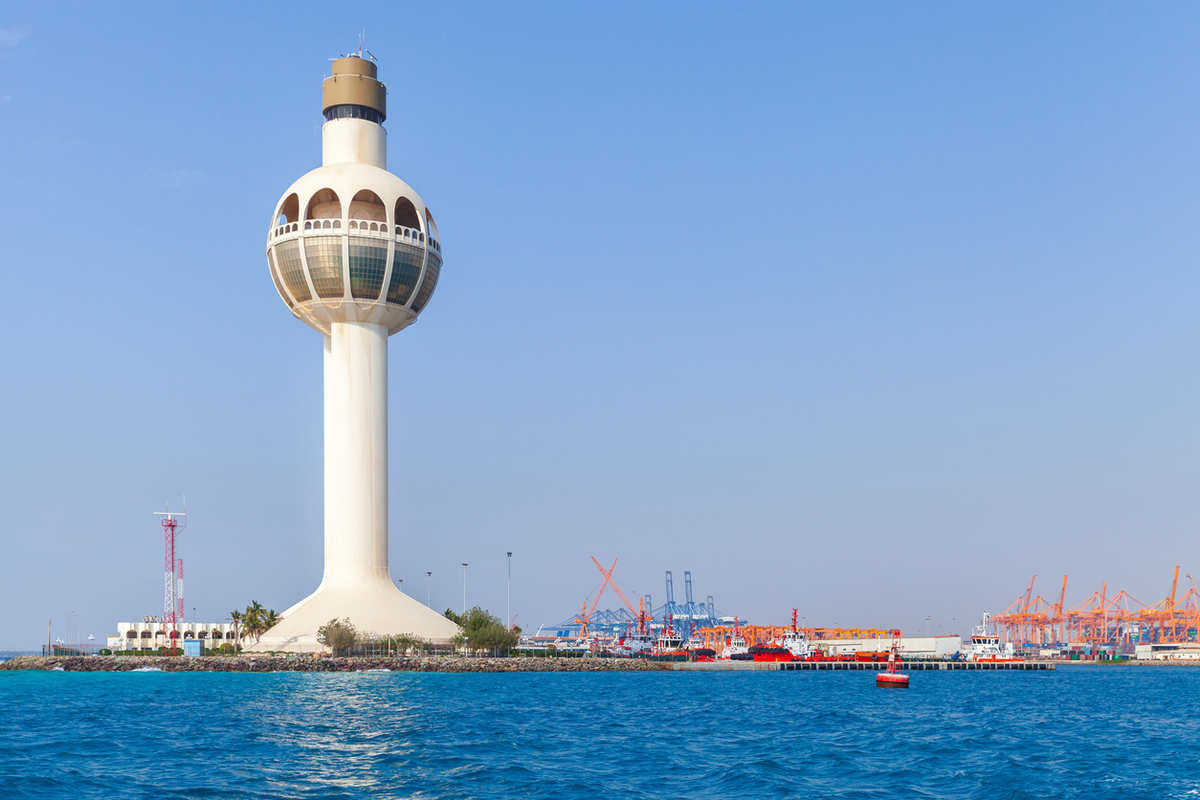 IMAGE: White lighthouse and traffic control tower in front of the Port of Jeddah, Saudi Arabia. Getty Images
Singapore and Malaysia
Despite muted demand, bunker availability in Singapore remains tight. Recommended lead times for VLSFO have widened to 13-16 days, from 12-15 days a week earlier. Most suppliers are carrying low stock levels, while delays in cargo arrivals have further tightened availability, according to a Singapore-based source.
HSFO supply has also come under greater pressure, with advised lead times extending to 10-19 days, compared with 10-12 days last week. LSMGO availability, however, has improved, with lead times narrowing to 6-8 days from 7-10 days previously.
At Port Klang, Malaysia, bunker supply remains constrained. Prompt VLSFO availability is particularly tight, while LSMGO supplies remain limited and HSFO continues to face pressure.
East Asia
Fuel availability in Zhoushan remains tight despite subdued demand, with suppliers quoting around 10 days for VLSFO, LSMGO and HSFO deliveries.
VLSFO lead times are largely unchanged from the previous week, as repeated weather disruptions continue to weigh on supply. Bunkering operations were suspended for roughly two weeks after Typhoon Dolphin struck in early August, creating significant delivery backlogs. Conditions tightened again towards the end of August, when rough seas associated with four consecutive tropical systems forced another suspension at Zhoushan’s inner and outer anchorages.
Operations resumed on 31 August at the more sheltered Xiushandong and inner Mazhi anchorages following a six-day weather-related shutdown. However, Xiushandong was forced to suspend bunkering again on 3 September after Typhoon Saudel made its third landfall in China along the Fujian coast. Operations restarted on 7 September.
Suppliers remain unsure when Zhoushan will return to full bunkering capacity, with operations still highly dependent on weather conditions.
Supply availability is mixed across other Chinese ports. Dalian and Qingdao have adequate VLSFO and LSMGO stocks, although HSFO remains tight in Qingdao. Tianjin is facing shortages across all three major grades, while Shanghai has limited VLSFO and HSFO availability but relatively stable LSMGO supply.
Southern Chinese ports are also under pressure. Fuzhou is short of VLSFO and LSMGO, while Xiamen has sufficient VLSFO but limited LSMGO. Supplies of both grades remain constrained in Yangpu and Guangzhou.
Hong Kong’s bunker market is broadly unchanged, with suppliers maintaining lead times of around seven days across the major grades.
In Taiwan, lead times at Keelung, Taichung, Kaohsiung and Hualien remain around two days for both VLSFO and LSMGO, little changed from the previous week.
Bunker demand in South Korea has strengthened despite higher Brent futures pushing fuel prices upward. VLSFO prices in Busan have increased by around $40/mt over the past week to approximately $970/mt, according to a South Korean trader.
Supply conditions have improved marginally at southern ports such as Busan, Ulsan, Masan, Onsan, Yeosu and Kwangyang. Lead times for all grades have shortened to 6-10 days from 7-11 days a week earlier. Western ports, including Incheon, Daesan, Dangjin, Pyeongtaek and Taean, have seen a similar improvement, with lead times for VLSFO, LSMGO and HSFO also narrowing to 6-10 days.
However, further weather disruptions are expected. Bunkering operations at Busan and Ulsan could be affected between 16 and 23 September, while Yeosu may face disruption from 17-22 September and Daesan on 17-18 September.
Japan’s bunker market remains particularly constrained. Although operational issues have reportedly been resolved, marine fuel cargo loadings for September remain severely restricted and are effectively unavailable. Refinery schedules for October and beyond are still pending.
“The market remains extremely tight,” a Japan-based trader said, adding that fresh spot offers are virtually non-existent and suppliers are quoting only on a strict subject-to-inquiry and confirmation basis.
Weather risks could add further pressure. A tropical depression south of Japan is expected to strengthen into a typhoon and could approach Okinawa and Japan’s Pacific coast during the Silver Week holiday from 19-23 September. Such conditions could cause significant berthing delays and further disrupt already strained supply logistics.
Given the holiday period and exceptionally tight market, the trader recommended arranging bunker requirements well in advance.
Availability of VLSFO, LSMGO and HSFO has tightened across several Japanese ports, including Tokyo, Chiba, Kawasaki, Nagoya, Yokkaichi, Osaka, Kobe, Mizushima, Tokuyama and Oita. Supplies across grades are virtually unavailable for September, while October and later stems remain subject to inquiry. Kashima continues to face tight availability of VLSFO and HSFO.
In contrast, Indonesia continues to enjoy healthy bunker fuel availability. Suppliers in Jakarta, Surabaya, Balikpapan and Cigading are generally recommending lead times of just 2-3 days for VLSFO.
Oceania
Bunker fuel supply in Western Australia remains stable, with VLSFO readily available at Kwinana and Fremantle. Suppliers at both ports are quoting lead times of around seven days. Each location is served by a single supplier, with all deliveries conducted by barge.
Supply conditions are more mixed along Australia’s east coast. At Port Kembla, VLSFO can be delivered by truck or pipeline, while Sydney has adequate availability of both VLSFO and LSMGO. HSFO supply in Sydney is comparatively tighter, with suppliers generally requiring around seven days’ notice.
Further north, Brisbane and Gladstone have ample VLSFO and LSMGO, with delivery lead times of roughly one week. In Melbourne and Geelong, VLSFO stocks remain comfortable, although both ports depend on a single bunker barge, keeping lead times at around seven days. HSFO availability has tightened further in both, Melbourne and Brisbane.
Separately, a supplier is offering VLSFO, LSMGO and HSFO at Brisbane, Sydney and Melbourne with shorter lead times of approximately five days.
In Western Australia, pipeline bunkering at Dampier Cargo Wharf (DCW) is expected to remain suspended until around the end of September while repair work continues. Limited truck deliveries are available, subject to vessel size. During the disruption, the supplier has designated the Toll Supply Base (TSB) in Dampier as the preferred bunkering point, according to a source.
Across the Tasman, New Zealand’s bunker market remains broadly stable. VLSFO is readily available at Tauranga and Auckland, with suppliers quoting lead times of around four days. At Marsden Point, vessels can receive both VLSFO and LSMGO directly through the pipeline.
Weather remains the principal operational risk in New Zealand. Wellington and ports across the South Island are particularly vulnerable to bunker delivery delays when adverse conditions disrupt marine operations.
South Asia
Bunker lead times of around 2-3 days are recommended for all three major fuel grades at several key Indian ports, including Mumbai, Cochin, Paradip, Visakhapatnam, Kakinada, Haldia, Chennai, Tuticorin and New Mangalore, according to an India-based source.
Weather could add pressure to bunker operations in the coming days, with rough conditions expected to disrupt deliveries at Sikka on 16 September.
In Sri Lanka, lead times for all major grades remain at around eight days at both Colombo and Hambantota, broadly unchanged from last week. Weather-related interruptions are also forecast at Colombo from 15-22 September and Trincomalee from 16-23 September, which could cause delays to bunker deliveries.
Middle East
Bunker fuel availability in Fujairah remains severely constrained as tensions between the US and Iran continue to disrupt shipping through the Strait of Hormuz. Supplies of all major grades are described as “super tight”, with fuel oil imports falling sharply amid heightened regional uncertainty.
Similar supply pressure is being reported at nearby Khor Fakkan, where availability across all grades remains limited, according to a Middle East-based source.
In Saudi Arabia, VLSFO and LSMGO availability at Jeddah remains steady. At Ras Laffan in Qatar, however, supplies of both grades remain restricted.
Across Oman, LSMGO availability is stable at key ports including Salalah, Muscat, Duqm and Sohar. Suppliers are recommending lead times of just 1-2 days, depending on the port and nomination.
In Egypt, bunker inventories at Port Suez have fallen to critically low levels across all three conventional fuel grades. Further south, Djibouti is also facing limited availability across all major grades.
By Tuhin Roy
Please get in touch with comments or additional info to news@engine.online