Europe & Africa Market Update 6 Nov
Bunker prices in European and African ports have mostly gained, while prompt fuel availability is tight in the ARA ports.
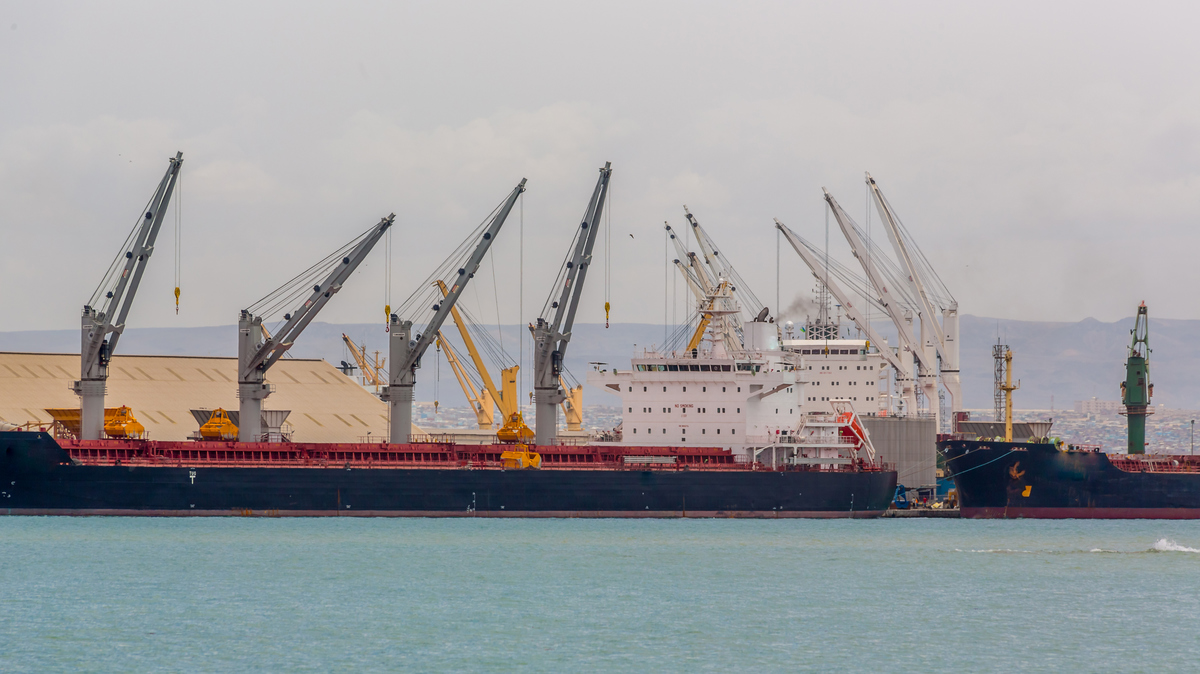
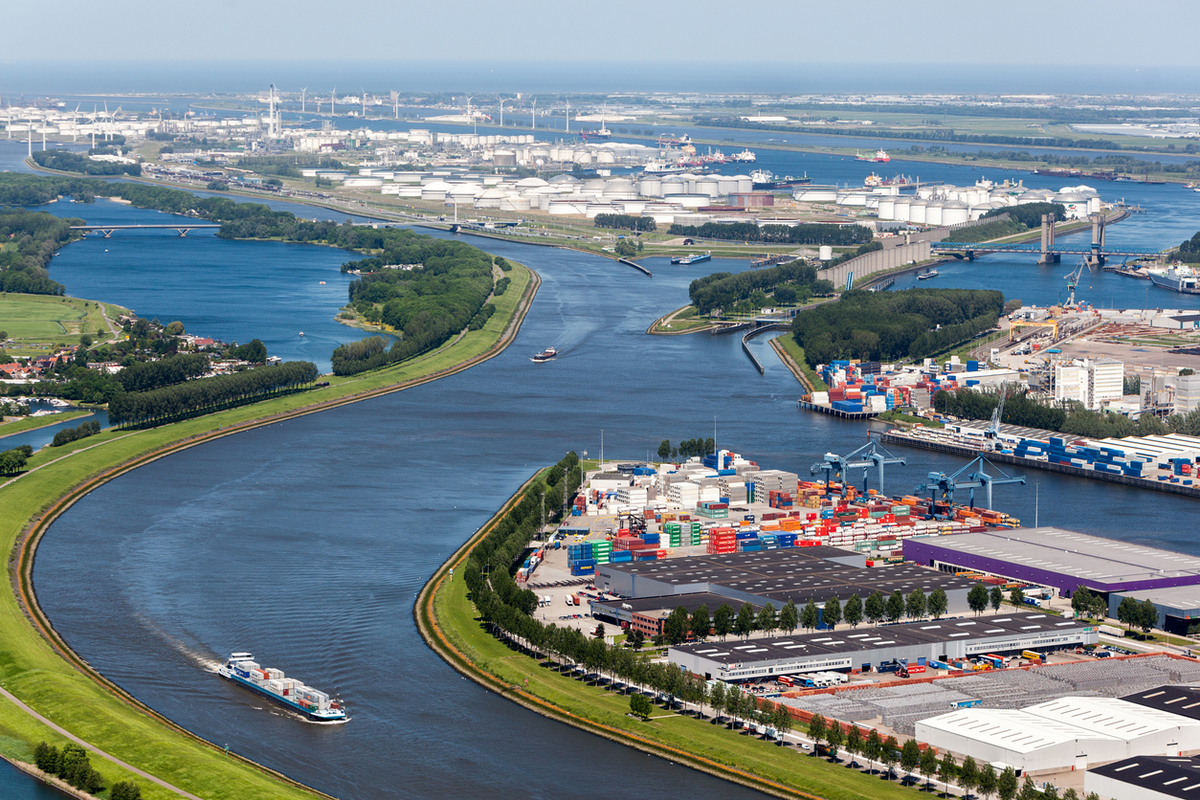 IMAGE: The Europoort area in the Port of Rotterdam. Getty Images
Changes on the day to 09.00 GMT today:
- VLSFO prices up in Rotterdam ($36/mt) and Gibraltar ($32/mt), and down in Durban ($46/mt)
- LSMGO prices up in Rotterdam ($100/mt), Durban ($99/mt) and Gibraltar ($51/mt)
- HSFO prices up in Gibraltar ($25/mt) and Durban ($5/mt), and down in Rotterdam ($27/mt)
- B30-VLSFO price down in Rotterdam ($76/mt)
Bunker benchmarks have gained over the past day, tracking Brent’s increase.
However, bucking the larger market trend, Rotterdam’s HSFO price has dropped, potentially pressured by a lower-priced, 500-1,500 mt stem, fixed at $570/mt.
Meanwhile, Rotterdam’s VLSFO price has increased. The diverging movements have widened the port’s Hi5 spread by $63/mt in a single day.
The Dutch port’s LSMGO price has increased more sharply than Gibraltar’s LSMGO price. This was possibly influenced by two higher-priced stems, fixed between $1,318-1,366/mt. This has narrowed the port’s LSMGO discount to Gibraltar by $49/mt, to $34/mt.
Meanwhile, Rotterdam’s B100 price has a $189/mt discount to LSMGO price.
That heavy discount has increased B100’s demand in the Dutch port, market sources said.
Fuel availability is tight in the port with buyers advised booking around 5-7 days ahead to get more coverage from suppliers, a trader told ENGINE.
Brent
The front-month ICE Brent contract has risen by $2.35/bbl on the day, to trade at $97.66/bbl at 09.00 GMT.
Upward pressure
Ongoing concerns over Middle Eastern oil supplies amid the conflict continue to support Brent crude futures.
Prices rebounded following a surge in tanker attacks in the Gulf and the Strait of Hormuz on Wednesday and Thursday. Renewed attacks in the strait, a critical maritime passage through which most Middle Eastern oil shipments transit, have heightened concerns over potential disruptions to regional supply flows, Reuters reported.
“The market has a habit of trying to sprint to the final chapter while the fighting is still on page one… Then comes another reminder from the Strait of Hormuz that wars do not end because the market grows tired of carrying the headline risk,” said SPI Asset Management managing partner Stephen Innes.
Brent crude has also drawn support from a further decline in US crude and fuel inventories. Commercial crude stocks in the US fell by 865,000 bbls to 409.8 million bbls in the week ended 30 October, according to the US Energy Information Administration (EIA).
Downward pressure
Meanwhile, expectations of a possible de-escalation in the US-Iran conflict have exerted downward pressure on oil prices following election losses for US President Donald Trump’s party.
“Brent, the global benchmark had come under pressure as the market contemplated what a Democrat sweep in US midterms elections would mean for the Middle East conflict,” said ANZ Bank senior commodity strategist Daniel Hynes.
“The political centre of gravity in Washington has shifted after the Democratic sweep, and that raises a much more awkward question for the White House: not whether it can launch another strike, but whether it still has the domestic room to sustain the war,” Innes said.
By Nachiket Tekawade and Tuhin Roy
Please get in touch with comments or additional info to news@engine.online